


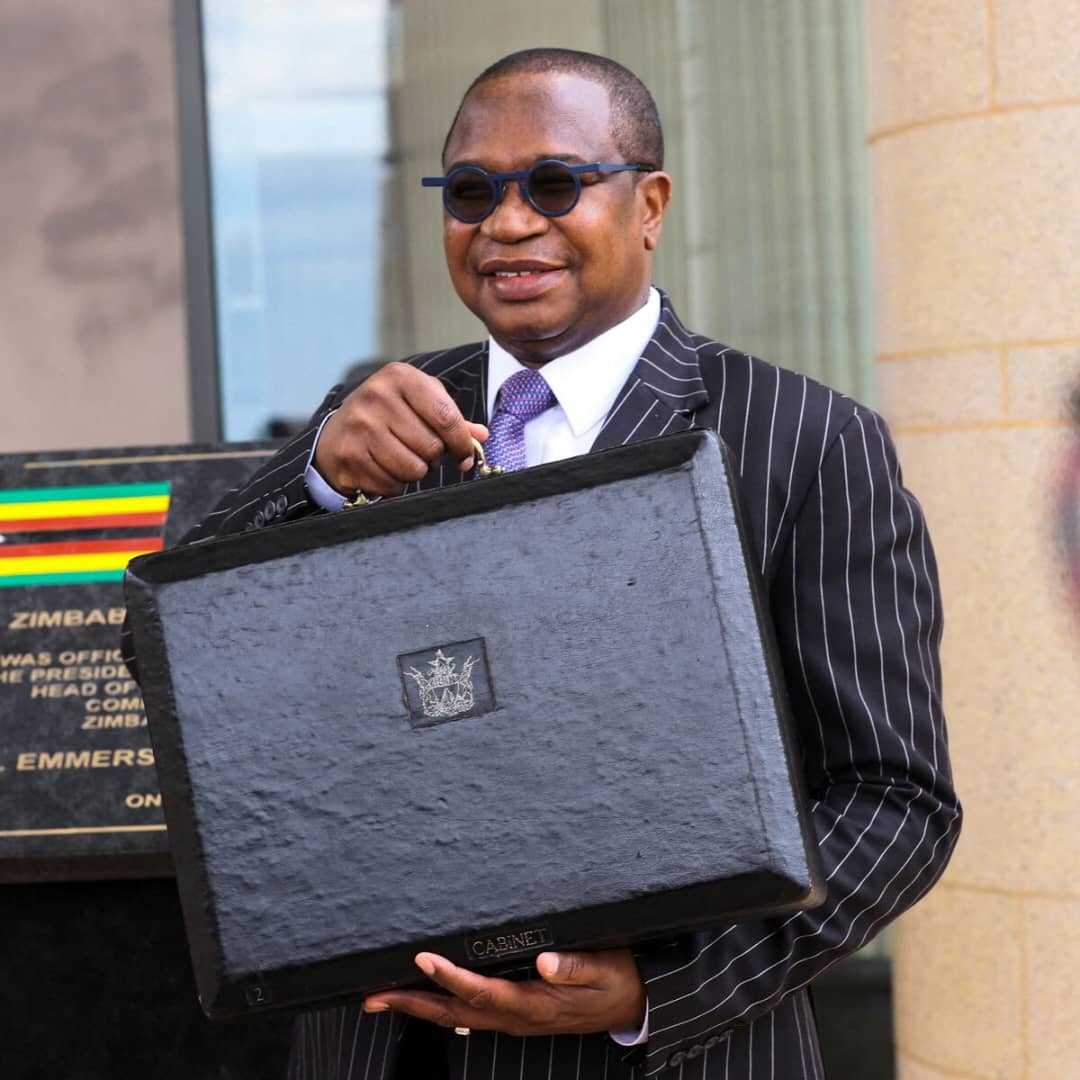
Zimbabwe has introduced a fixed timetable for the preparation of the national budget, requiring ministries to submit spending proposals by September 30 and the Finance Minister to take the final budget to Parliament no later than the third Thursday of November.
The changes are contained in Statutory Instrument 153 of 2026, the Public Finance Management (General) (Amendment) Regulations, 2026 (No. 2), which amend the 2019 public finance regulations and repeal the 2021 amendment.
The new framework provides that “the Minister shall determine the annual budget process” according to a prescribed sequence running from June to the final parliamentary approval of the budget.
Under the timetable, ministries, departments and agencies must provide their input into the Budget Strategy Paper and Mid-Year Budget and Economic Review by June 1, including “revised strategic priorities and expenditure intentions”.
The Finance Minister must present the Budget Strategy Paper and Mid-Year Fiscal Review to Cabinet by July 15 and to Parliament by July 31, giving legislators an earlier formal opportunity to examine the government's fiscal position before the main budget.
Treasury must then update its macroeconomic performance and forecasts by September 1 and issue the second Budget Call Circular, containing “expenditure ceilings for the medium term”, by September 10.
That ceiling is followed by a firm deadline for ministries to put their spending demands on the table. The SI requires MDAs to provide their budget submissions to the Finance Ministry “by 30th September”, after which Treasury is required to hold budget discussions with ministries, departments and agencies “between 1st October to 21st October”.
Related Stories
The sequence effectively compresses the final stages of budget preparation into a defined October negotiation period, giving Treasury a specified window to reconcile ministries' spending demands with available resources and the expenditure ceilings already communicated.
The regulations then move the process into Cabinet before setting a parliamentary deadline. The Finance Minister must present the proposed budget to Cabinet during a November Cabinet meeting before taking it to Parliament.
The final requirement is explicit: the Finance Minister must “present Budget to Parliament no later than the 3rd Thursday of November”, after which the budget is “debated and approved”.
The significance of the changes is less about creating a new budget process than imposing deadlines on the existing one. The calendar creates identifiable points at which ministries must submit priorities, Treasury must establish medium-term ceilings, negotiations must take place and Parliament must receive the final budget.
That could improve predictability in public finance management if the deadlines are observed consistently. It also gives Parliament a defined timetable for receiving the government's fiscal plans rather than leaving the timing of key budget documents largely dependent on the administrative process.
The September deadline for ministries is particularly important because it requires spending proposals to be submitted before the October negotiations. This creates a clearer separation between the identification of expenditure requirements and Treasury's subsequent negotiations over what can be accommodated within the available fiscal space.
The regulations also formalise an earlier parliamentary intervention through the requirement that the Budget Strategy Paper and Mid-Year Fiscal Review be presented to Parliament by July 31. This potentially gives lawmakers greater visibility over changes in revenue, expenditure and macroeconomic assumptions several months before the main budget.
However, the fixed calendar does not by itself guarantee stronger fiscal discipline. Its effectiveness depends on whether ministries meet the deadlines, whether Treasury's expenditure ceilings are credible, and whether subsequent budget allocations remain aligned with the framework established during the June-to-October process.
Leave Comments